AI Analysis · Investment Score
AI Investment Score.
A personalised 0–100 score for the property you are considering — affordability, appreciation, rental yield, risk and liquidity, weighted to what you are actually trying to achieve.
Investment Analysis Setup
Provide your financial and property details to get AI-powered investment insights
Free advisory
Not sure which project to score? We will shortlist for you.
The score is only as useful as the shortlist you feed it. Tell us your budget and where you want to live, and we will come back with RERA-verified Bengaluru projects worth scoring — at no cost, and no brokerage either, because the developer pays us and you do not.
Brokerage
ZERO
RERA
VERIFIED
Projects analysed
BENGALURU-WIDE
Already scored
Browse all listingsBengaluru homes we have run the numbers on.
Every listing we carry is RERA-verified and scored on the same five pillars, so you can start from a shortlist that already passed rather than a blank form.
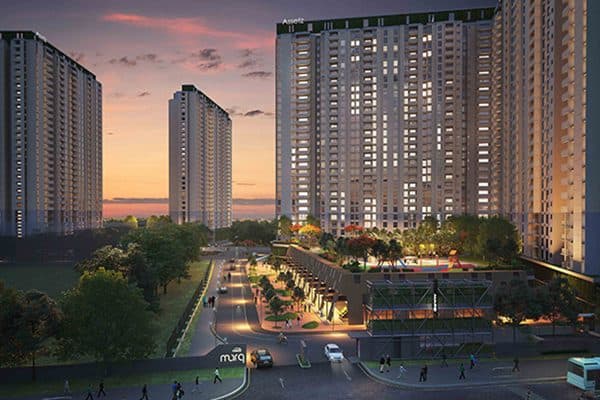
ready to_move
90Anvi Score
Assetz Marq - Resale
Whitefield, Bangalore
₹2.50 Cr
Onwards
3BHK, 4BHK, 2BHK1 sqft
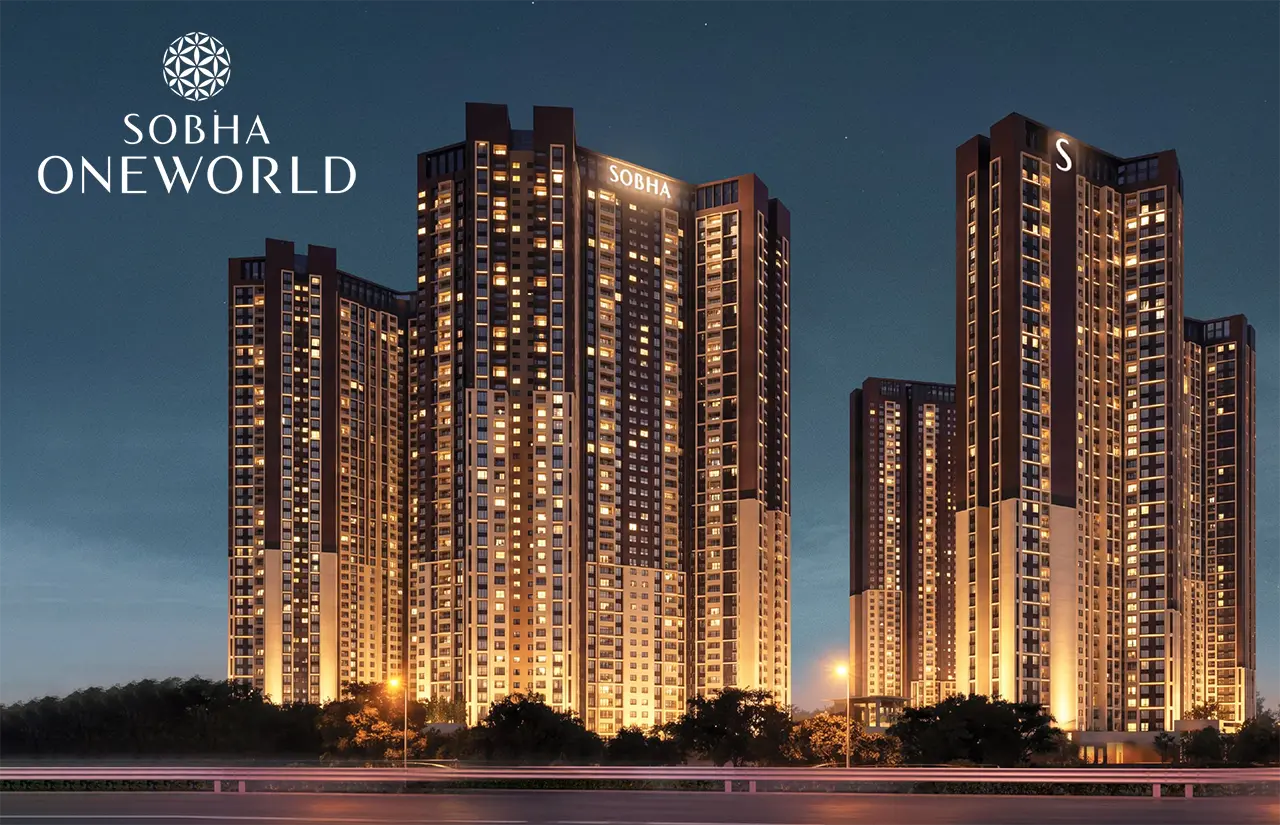
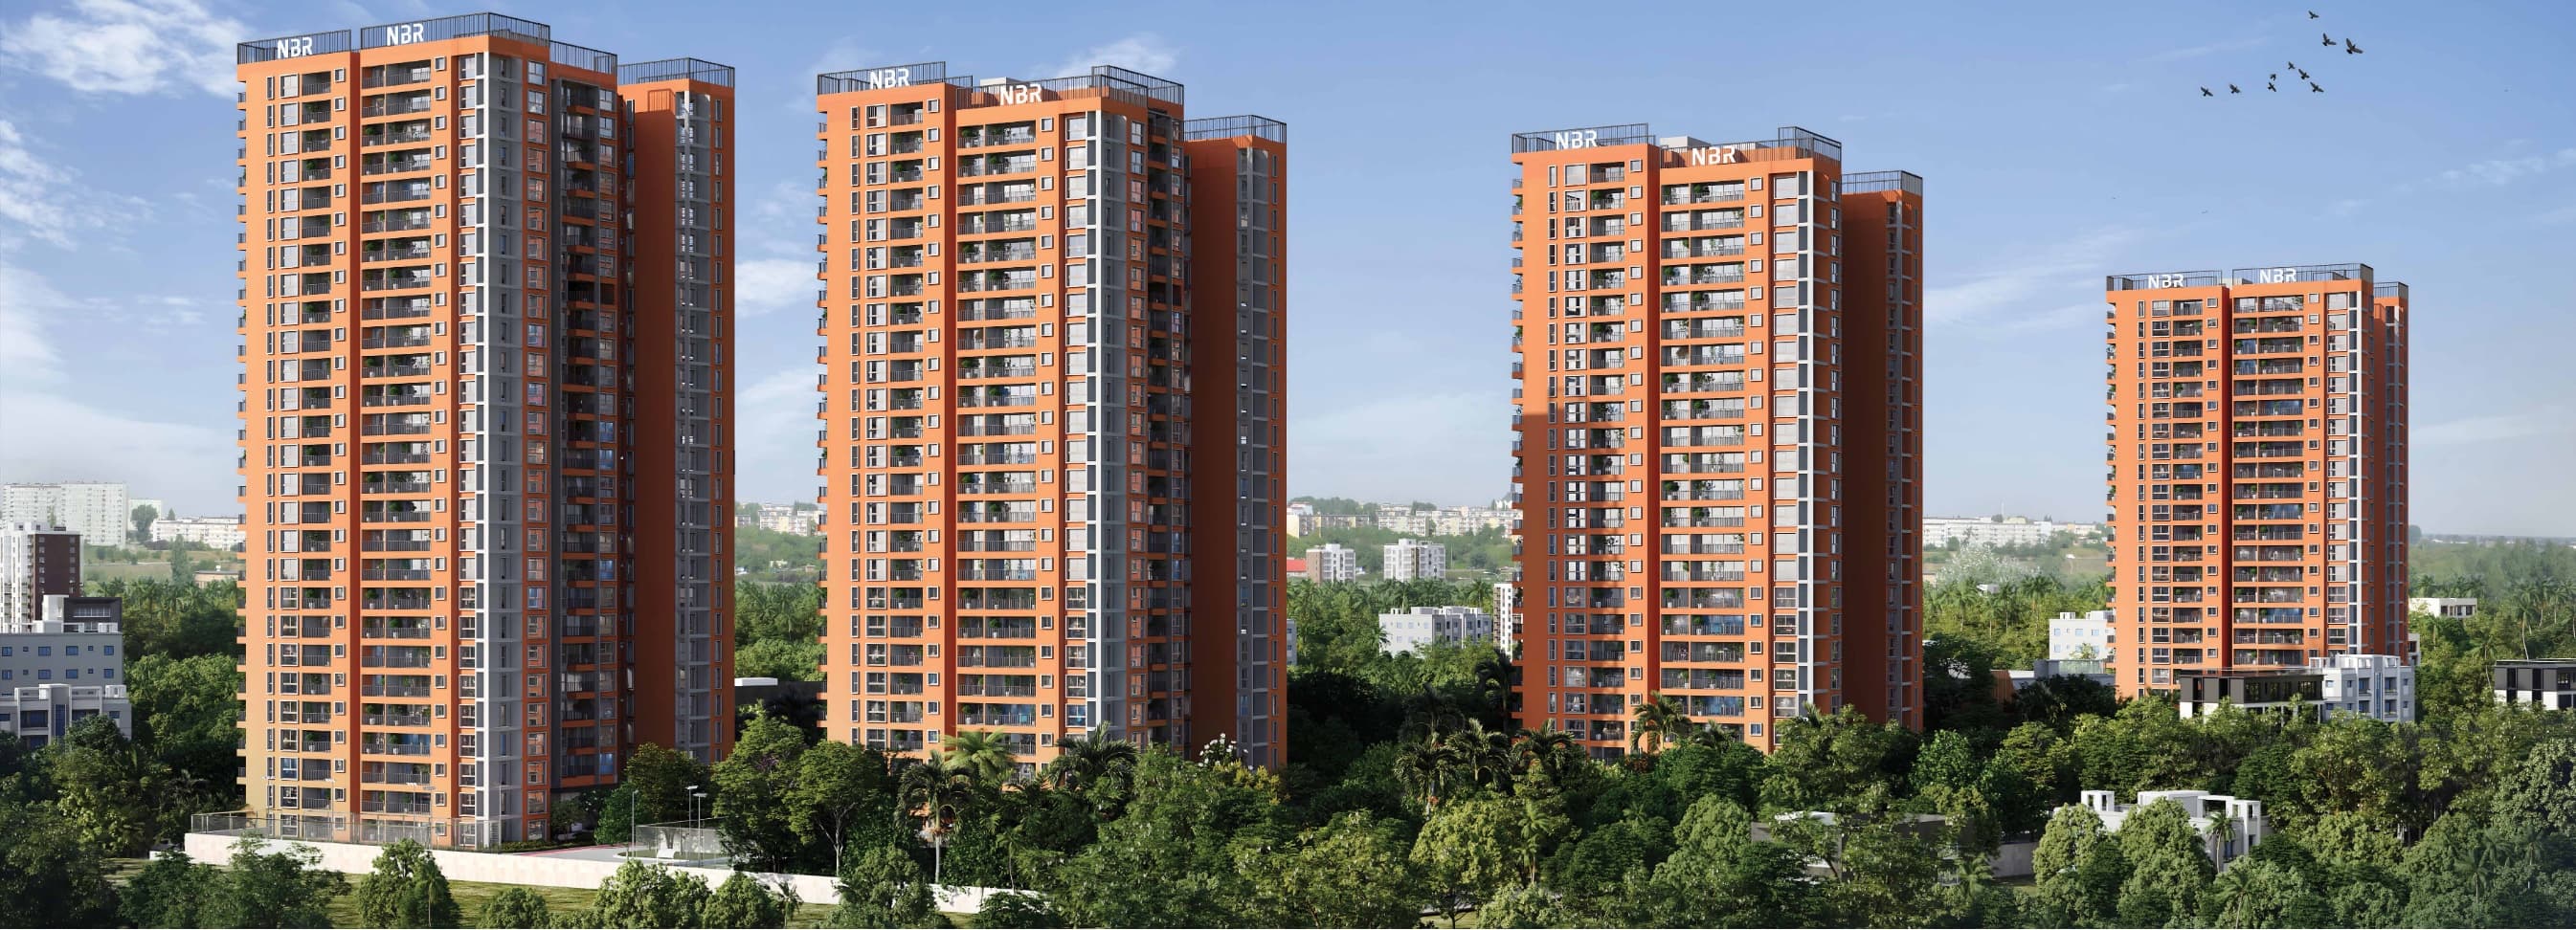
under construction
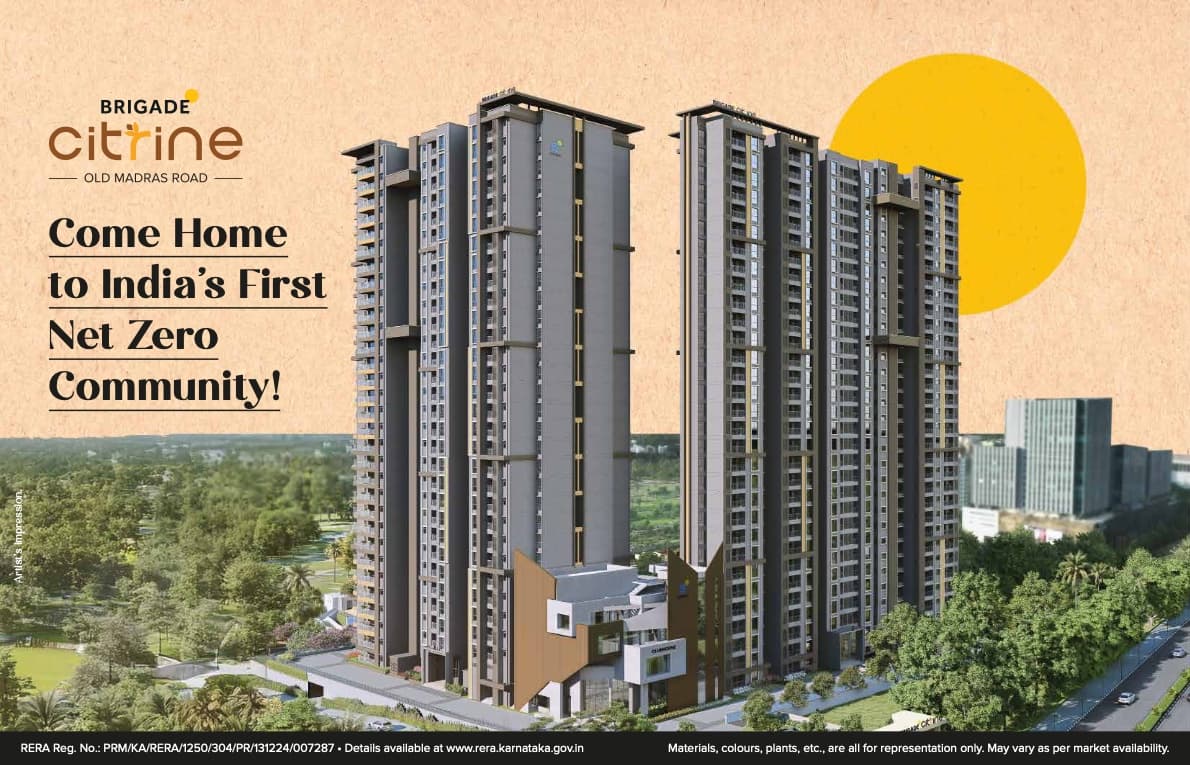
85Anvi Score
Brigade Citrine
Budigere Cross, Bangalore
₹2.07 Cr
Onwards
3BHK, 4BHK1738 sqft
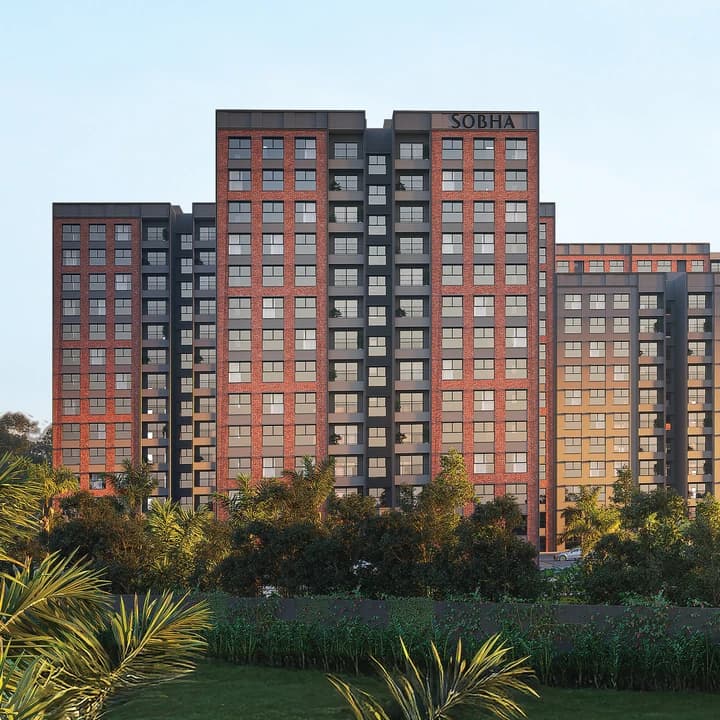
under construction
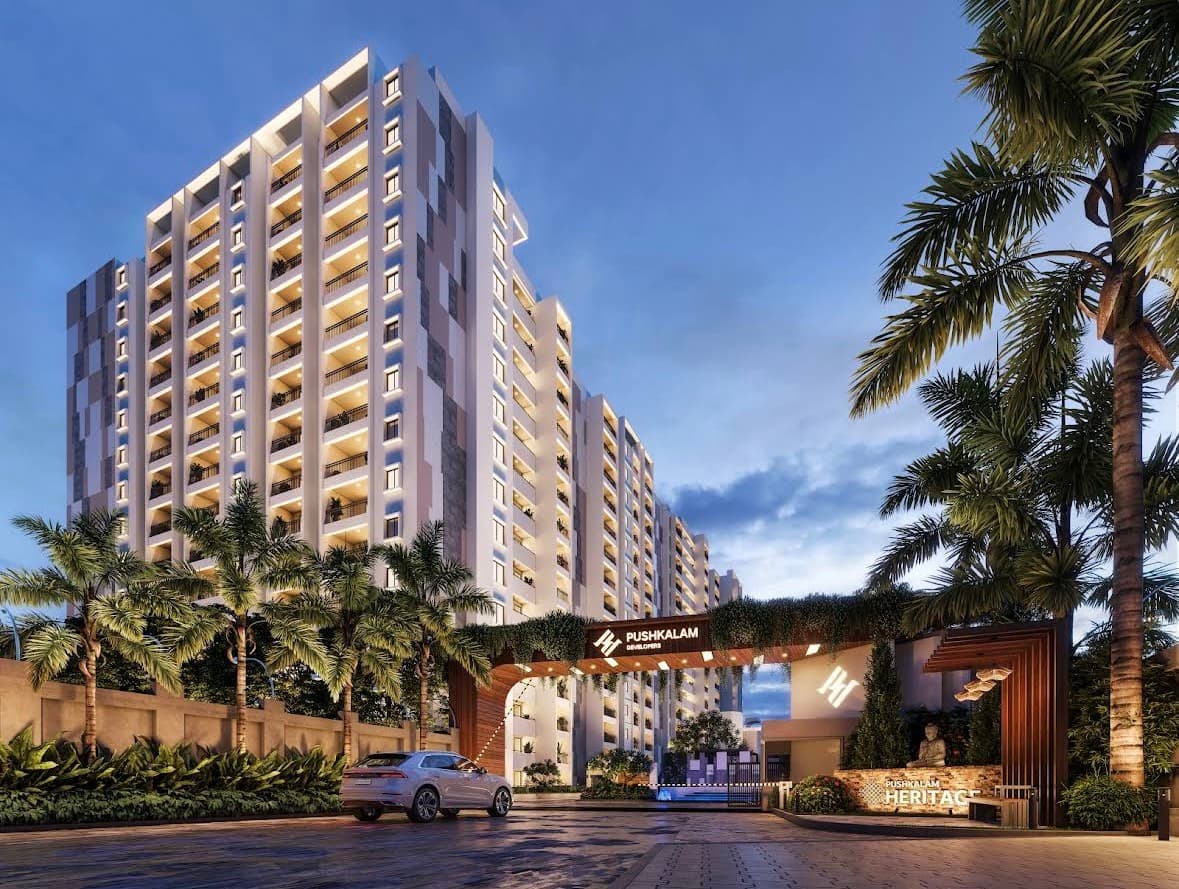
80Anvi Score
Pushkalam Heritage
Budigere Cross, Bangalore
₹1.30 Cr
Onwards
2BHK, 3BHK1310 sqft
Investment score questions, answered
What the score measures, what it cannot see, and how much of your decision it should carry.
What is an AI Investment Score?
It is a single 0–100 number summarising how good a specific property purchase looks for you — not for a generic buyer. The score is a weighted blend of five pillars: affordability, appreciation potential, rental yield, risk and liquidity. Think of it as a credit score in reverse: instead of rating you for a lender, it rates the purchase for you.
How is the score calculated?
Each of the five pillars is scored 0–100 from your inputs and our locality data, then combined using weights that shift with your stated investment goal. A balanced goal weights affordability 25%, appreciation 20%, rental yield 20%, risk 20% and liquidity 15%. Pick rental income instead and rental yield rises to 30%; pick capital growth and appreciation rises to 30% with liquidity at 20%. The result is rounded to a whole number and graded.
What counts as a good score?
85 and above is an excellent opportunity — the purchase is comfortably affordable and the fundamentals support it. The 70s and low 80s are solid with specific caveats worth reading. Below 50 means at least one pillar is working strongly against you, most often affordability or risk, and the report will name which. A low score is not a verdict on the property so much as on this property for you, at this price, on these finances.
What information do I need to provide?
Your monthly income, existing EMIs and available savings on the financial side; the property price, type, locality, expected rent and carpet area on the property side; and your loan rate, tenure and down payment on the financing side. Nothing is mandatory to the rupee — where you leave a field blank we fall back on market defaults for your city and say so in the report.
Is my financial data stored or shared?
Your inputs are used to compute the score and are not sold or shared with third parties. The report is generated for your session and can be downloaded as a PDF. If you choose to speak to an advisor we use only the details you explicitly submit for that purpose.
Does a high score mean I should buy?
No. The score is an input to your decision, not a substitute for it. It cannot see the things that most often ruin a purchase — a builder who does not deliver, a title problem, an approval that never arrives, a job change six months out. Use the score to compare shortlisted options on comparable terms, then verify the project itself: RERA registration, the builder's delivery record, and the locality's fundamentals.
How is this different from a rental yield or EMI calculator?
Those answer one question each — what the instalment is, what the yield is. The investment score weighs those answers against each other and against your finances, so a property with a great yield you cannot actually afford scores badly, and an expensive property you can carry comfortably in a strong locality scores well. It is the difference between a measurement and a judgement.
Is the AI Investment Score free?
Yes, and there is no brokerage either — AnviRealty is paid by the developer, not by the buyer. You can score as many properties as you like and download each report.
Keep planning
Property Pulse
Before the project, check whether the market is timed in your favour.
Bangalore Rent Tracker
Sanity-check the rent you assumed against what the locality really gets.
Home Loan EMI Calculator
Monthly instalment, total interest and the full repayment schedule.
Rental Yield Calculator
Gross and net yield on a property you plan to let out.
Resale Value Calculator
Project what your property could be worth when you exit.
Hidden Costs Calculator
GST, khata, deposits and the charges nobody quotes upfront.