Financial Tools · Home Loan
Home Loan OD Calculator.
Park your spare cash in your home loan account and you pay less interest — without locking the money away. See what you would save, and how much sooner the loan ends.
Your home loan
₹50.00 L
₹
%
%
Years
The OD runs at 7.75%. Most lenders charge 0.1–0.5% more for it than for their plain home loan — ask yours for both rates.
Money you park in the account
₹10.00 L
₹
Add a bonus, a monthly amount you save from salary, or money you'll need to take out later.
This money is not gone. It sits in your account and you can withdraw it any day you need it — the savings below simply stop for the days it is out.
What it saves you
Interest you don’t pay
₹23,38,651
50.1% less interest than a normal loan
Your loan finishes early
5 years 1 month sooner
You clear the loan in 14 years 11 months instead of 20 years — paying the same instalment the whole way.
From year 13, month 12 your parked cash covers everything you owe. You could close the loan then, instead of paying EMIs on money you already hold.
Your OD EMI
₹41,047
fixed; ₹768 above a normal loan
Break-even balance
₹50,964
kept parked throughout, to beat a normal loan
Total interest, with the OD₹23.28 L
A normal loan at 7.5% would cost you ₹46.67 L in interest. The bar is what is left of that bill once your parked cash does its work.
This money earns no savings interest
With most lenders, cash sitting in an OD account earns no savings account interest at all. Nothing gets credited to you each quarter — the entire benefit is the smaller interest charge on your loan. That is still the better end of the deal: not paying 7.75% beats the 2.5–3% a savings account pays, and money you never pay out is not taxed the way interest income is.
Normal loan vs OD account
Same loan, same tenure. The OD costs 0.25% more, and every rupee parked in it is a rupee you pay no interest on.
You keep ₹23.39 L
Normal home loan
- Rate
- 7.5%
- Monthly instalment
- ₹40,280
- How long you pay
- 20 years
- Total interest
- ₹46,67,118
- Total you hand the bank
- ₹96,67,118
With an OD account
- Rate
- 7.75%
- Monthly instalment
- ₹41,047
- How long you pay
- 14 years 11 months
- Total interest
- ₹23,28,467
- Total you hand the bank
- ₹73,28,467
What you owe, year by year
The dashed line is what you really owe once your parked cash is netted off — the figure the bank charges interest on. Where it touches zero, the money in your account could close the loan.
How an OD home loan works
1
Your loan gets a bank account
The lender links your home loan to a savings or current account. Salary, bonus, rent, anything — it all goes in there as usual.
2
Interest is charged on the difference
Owe ₹50L and have ₹10L sitting in the account? The bank charges you interest on ₹40L for those days, not ₹50L.
3
The EMI stays, the loan shrinks faster
Your instalment does not change. Less of it goes on interest, so more of it repays the loan — and the loan ends years early.
Why people like it
Unlike a prepayment, the money is not locked away. Park it, save interest every day it stays, and pull it back out for an emergency, a school fee or a holiday without asking anyone's permission.
The catch
It only works if the money actually stays there. If you spend your salary by the 10th of every month, an OD saves you very little — and most lenders charge a slightly higher rate for the facility.
How this is worked out
Each loan's instalment is fixed once, on its own rate, and never changes. The normal loan runs at the rate you entered; the OD runs at that rate plus the extra you entered. Interest is worked out month by month on what you owe minus what is in the account, with each deposit, top-up or withdrawal applied at the start of its month. Real lenders calculate it daily, so your actual saving will land within a few thousand rupees of this figure either way.
Parking vs prepaying: with a fixed EMI, a rupee parked in the OD and a rupee prepaid off the loan save exactly the same interest. The only difference is that the parked rupee can still come back out — which is why prepaying into an OD rarely makes sense.
Your balance moves within the month. Salary that lands on the 1st and is spent by the 30th only counts for the days it sat there, so enter what you typically keep on average, not what arrives on payday.
Tax: under the old tax regime, home loan interest on a self-occupied home is deductible up to ₹2 lakh a year (Section 24(b)). Paying less interest means a slightly smaller deduction. It rarely changes the answer, but it is worth knowing if your interest is near that limit.
Free advisory
₹23.39 L saved on interest. Now pick the right property.
An OD account is a good way to pay less for a house. Choosing the right house is the bigger lever. AnviRealty scores every Bengaluru project on location, builder track record and rental fundamentals, at no cost to the buyer.
Brokerage
ZERO
RERA
VERIFIED
Projects analysed
BENGALURU-WIDE
Worth borrowing for
Browse all listingsBengaluru projects we stand behind.
An OD account saves you interest; the right property saves you far more. These are RERA-verified Bengaluru projects, each scored on location, builder track record and rental fundamentals.
ready to_move
90Anvi Score
Assetz Marq - Resale
Whitefield, Bangalore
₹2.50 Cr
Onwards
3BHK, 4BHK, 2BHK1 sqft
under construction
85Anvi Score
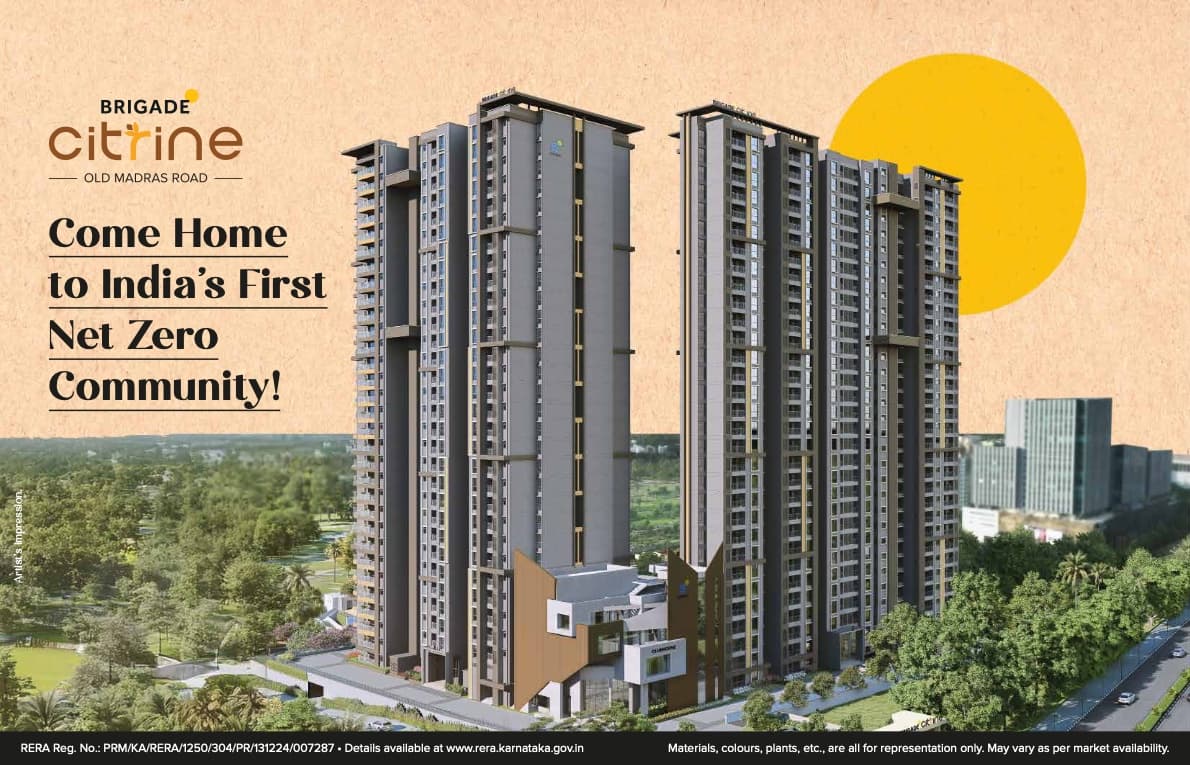
Brigade Citrine
Budigere Cross, Bangalore
₹2.07 Cr
Onwards
3BHK, 4BHK1738 sqft
under construction
80Anvi Score
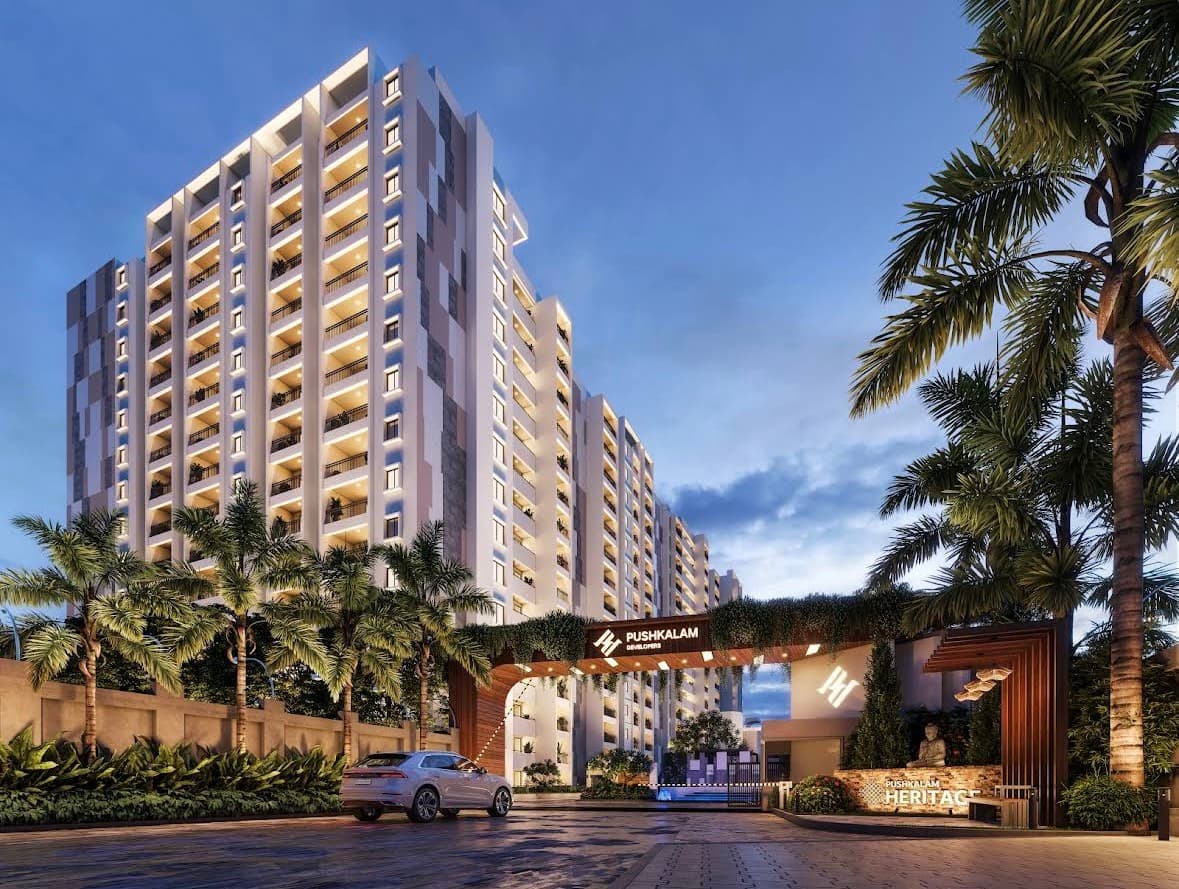
Pushkalam Heritage
Budigere Cross, Bangalore
₹1.30 Cr
Onwards
2BHK, 3BHK1310 sqft
Home loan OD questions, answered
Plain answers on how an OD home loan works, what it saves you, and whether it is worth it for you.
What is a Home Loan Overdraft (OD) facility?
A Home Loan OD is a special home loan product where your loan account is linked to a current or savings account. Any surplus funds you park in this linked account reduce your outstanding loan balance on a daily basis, which directly lowers the interest charged for that day.
How does parking money in an OD account save interest?
Home loan interest is calculated on the daily outstanding principal. When you deposit money into your OD-linked account, it effectively reduces the principal for that day. You still keep access to those funds, but every day they sit in the account saves you that day's interest. Over the loan tenure, even ₹1–2 lakh parked consistently can save several lakhs in interest.
Does my EMI go down if I park money in the OD account?
No — and this is the most common misunderstanding about OD home loans. Your monthly instalment stays exactly the same. What changes is what happens inside it: less of each instalment is swallowed by interest, so more of it goes towards repaying the loan. The benefit reaches you as a loan that ends years early, not as a smaller monthly payment. On a ₹50 lakh loan at 7.5% over 20 years, keeping ₹10 lakh parked throughout clears the loan almost five years ahead of schedule while the EMI never moves.
Can I withdraw money from the OD account whenever I need it?
Yes. The key advantage over a prepayment is flexibility — you can withdraw the parked funds anytime for emergencies or other expenses. When you withdraw, the effective principal goes back up and interest resumes on the higher balance.
Does the money I park in the OD account earn savings account interest?
With most OD home loans, no. The balance you keep in the account earns no savings interest — you will not see interest credited to you each quarter, and the balance is not treated like an ordinary savings deposit. Its only job is to reduce the amount the lender charges you interest on. In practice that is the better arrangement: on a loan at 7.5% you are effectively getting 7.5% by not paying it, against the 2.5–3% a savings account pays. It is also cleaner on tax, because savings and fixed deposit interest is taxable income, while interest you simply never pay is not. The one thing to watch is that a few lenders structure the product differently, so confirm with yours whether the parked balance earns anything.
Is a Home Loan OD rate higher than a regular home loan?
Typically yes — the interest rate on an OD home loan may be marginally higher than a standard home loan from the same lender. Whether the OD is beneficial depends on how consistently you can keep a surplus parked. If you plan to leave a significant amount idle for long periods, the interest savings generally outweigh the rate difference. The calculator shows the break-even: the smallest balance you would need to keep parked for the OD to cost no more than a plain loan.
Who should consider a Home Loan OD?
It works best for salaried professionals who receive a monthly salary and can leave it in the OD account until needed, business owners with seasonal cash surpluses, and anyone with a variable income who occasionally holds large amounts in savings. It is less useful if you spend your salary immediately each month.
Should I prepay my loan or park the money in the OD account?
If you already have an OD home loan, park it. With a fixed EMI, a rupee parked in the OD account and a rupee prepaid off the loan save exactly the same interest, month for month. The parked rupee can still be withdrawn; the prepaid one cannot. So prepaying into an OD gives up your flexibility and gets nothing back for it. The calculator lets you mark a deposit as a locked prepayment to see this — the interest saving does not change.
How is this different from making a prepayment?
A prepayment permanently reduces the principal — you cannot get that money back without taking a new loan. An OD deposit achieves the same interest saving while the money is parked, but the funds remain accessible. The tradeoff is that you need the discipline to actually keep the money in the account.
Keep planning
Home Loan EMI Calculator
The baseline instalment an OD account works against.
Pre-EMI Calculator
What an under-construction home costs you before possession.
Hidden Costs Calculator
GST, khata, deposits and the charges nobody quotes upfront.
Stamp Duty Calculator
State-wise stamp duty and registration charges on your purchase.
Rent vs Buy Calculator
Whether buying beats renting over your actual holding period.
AI Investment Score
Score the project you are buying into before you commit.