Financial Tools · EMI
Home Loan EMI Calculator.
Work out your monthly instalment, the total interest you will pay, and how much a prepayment takes off the bill.
Your loan
What you will pay
Your monthly EMI
₹40,280
Over 20 years you repay ₹96.67 L for the ₹50 L you borrow. ₹46.67 L of that is interest.
Total payable
₹96.67 L
Total interest
₹46.67 L
Cost of ₹1
₹1.93
Early EMIs are mostly interest
In year 1 only 23% of what you pay repays the loan; the rest is interest. Principal overtakes interest in year 12. That is why prepaying in the first few years saves the most.
What you need to earn
Lenders usually cap EMIs at about 40% of take-home pay. For this EMI that means roughly ₹1.01 L a month, before any other EMIs you already pay.
A 15-year loan costs far less
At 15 years your EMI is ₹46,351 (₹6,071 more a month) and you save ₹13.24 L in interest.
Where each year's EMIs go
Every year you pay about the same total. What changes is the split between interest and the loan itself.
Year-by-year schedule
| Year | EMIs paid | Principal | Interest | Still owed |
|---|---|---|---|---|
| 1 | ₹4,83,356 | ₹1,12,159 | ₹3,71,197 | ₹48,87,841 |
| 2 | ₹4,83,356 | ₹1,20,867 | ₹3,62,489 | ₹47,66,974 |
| 3 | ₹4,83,356 | ₹1,30,250 | ₹3,53,106 | ₹46,36,724 |
| 4 | ₹4,83,356 | ₹1,40,361 | ₹3,42,995 | ₹44,96,363 |
| 5 | ₹4,83,356 | ₹1,51,258 | ₹3,32,098 | ₹43,45,105 |
| 6 | ₹4,83,356 | ₹1,63,001 | ₹3,20,355 | ₹41,82,104 |
| 7 | ₹4,83,356 | ₹1,75,655 | ₹3,07,701 | ₹40,06,450 |
| 8 | ₹4,83,356 | ₹1,89,291 | ₹2,94,065 | ₹38,17,158 |
| 9 | ₹4,83,356 | ₹2,03,986 | ₹2,79,369 | ₹36,13,172 |
| 10 | ₹4,83,356 | ₹2,19,822 | ₹2,63,534 | ₹33,93,350 |
| 11 | ₹4,83,356 | ₹2,36,888 | ₹2,46,468 | ₹31,56,462 |
| 12 | ₹4,83,356 | ₹2,55,278 | ₹2,28,078 | ₹29,01,184 |
| 13 | ₹4,83,356 | ₹2,75,096 | ₹2,08,260 | ₹26,26,088 |
| 14 | ₹4,83,356 | ₹2,96,452 | ₹1,86,904 | ₹23,29,636 |
| 15 | ₹4,83,356 | ₹3,19,467 | ₹1,63,889 | ₹20,10,169 |
| 16 | ₹4,83,356 | ₹3,44,268 | ₹1,39,088 | ₹16,65,901 |
| 17 | ₹4,83,356 | ₹3,70,994 | ₹1,12,362 | ₹12,94,907 |
| 18 | ₹4,83,356 | ₹3,99,795 | ₹83,561 | ₹8,95,112 |
| 19 | ₹4,83,356 | ₹4,30,833 | ₹52,523 | ₹4,64,279 |
| 20 | ₹4,83,356 | ₹4,64,279 | ₹19,077 | ₹0 |
What a different tenure would cost
Same loan and rate, different length. A longer loan lowers the EMI and raises the interest.
| Tenure | Monthly EMI | Total interest | vs your plan |
|---|---|---|---|
| 10 years | ₹59,351 | ₹21.22 L | Save ₹25.45 L |
| 15 years | ₹46,351 | ₹33.43 L | Save ₹13.24 L |
| 20 years Your plan | ₹40,280 | ₹46.67 L | — |
| 25 years | ₹36,950 | ₹60.85 L | Pay ₹14.18 L |
| 30 years | ₹34,961 | ₹75.86 L | Pay ₹29.19 L |
How an EMI works
- 1
Interest is charged on what you still owe
On a ₹50 lakh loan at 7.5%, the first month's interest is ₹31,250.
- 2
Your EMI never changes
Your ₹40,280 EMI covers that interest first. Only the ₹9,030 left over repays the loan.
- 3
So the balance falls slowly, then faster
As the balance drops, less of each EMI is interest and more repays the loan. A prepayment early on shrinks the balance that interest is charged on.
Free advisory
₹40,280 a month for 20 years? Make sure the asset is worth it.
An instalment you can carry tells you nothing about whether the property will hold its value. AnviRealty scores every Bengaluru project on location, builder track record and rental fundamentals — and the buyer pays us nothing for it.
Brokerage
ZERO
RERA
VERIFIED
Projects analysed
BENGALURU-WIDE
Homes that fit this EMI
Browse all listingsBengaluru homes worth the instalment.
An EMI is a twenty-year commitment to a specific building. These are RERA-verified Bengaluru projects, each scored on location, builder track record and rental fundamentals.
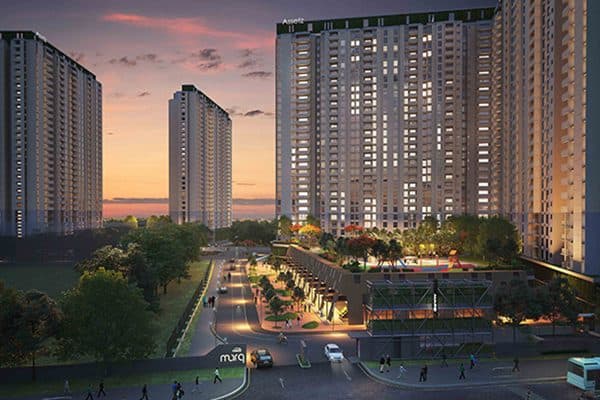
ready to_move
90Anvi Score
Assetz Marq - Resale
Whitefield, Bangalore
₹2.50 Cr
Onwards
3BHK, 4BHK, 2BHK1 sqft
under construction
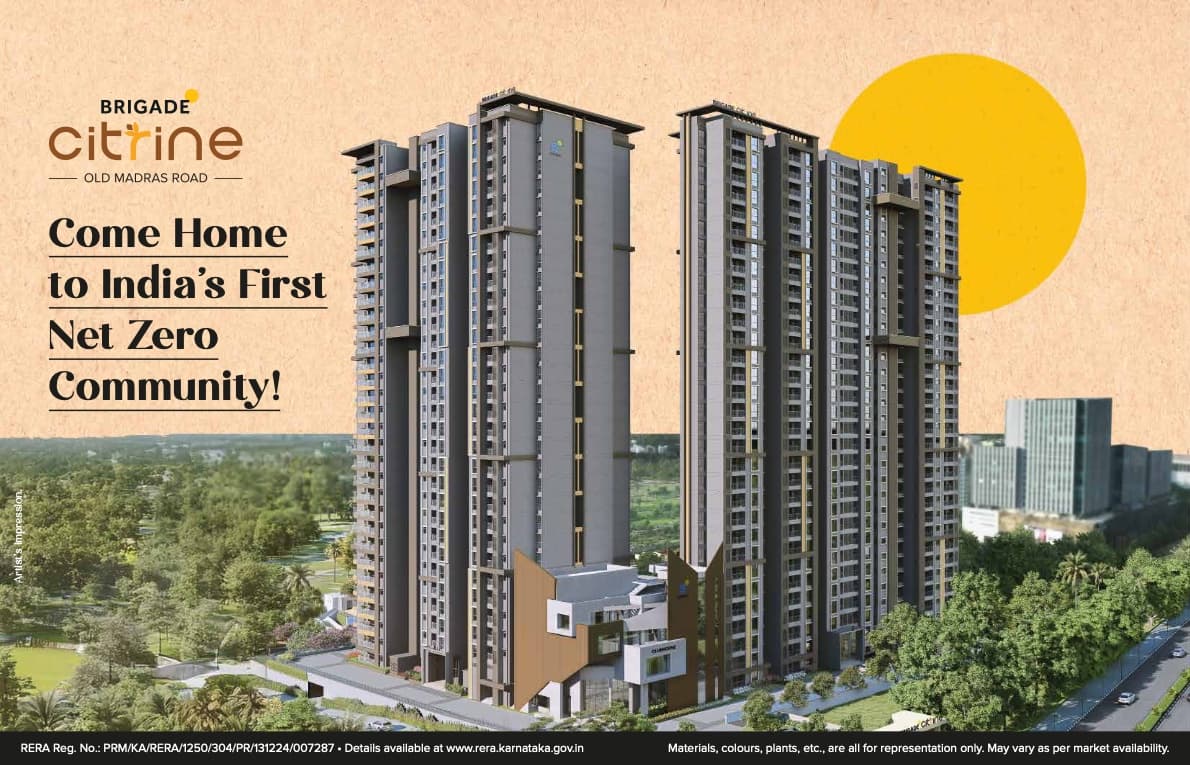
85Anvi Score
Brigade Citrine
Budigere Cross, Bangalore
₹2.07 Cr
Onwards
3BHK, 4BHK1738 sqft
under construction
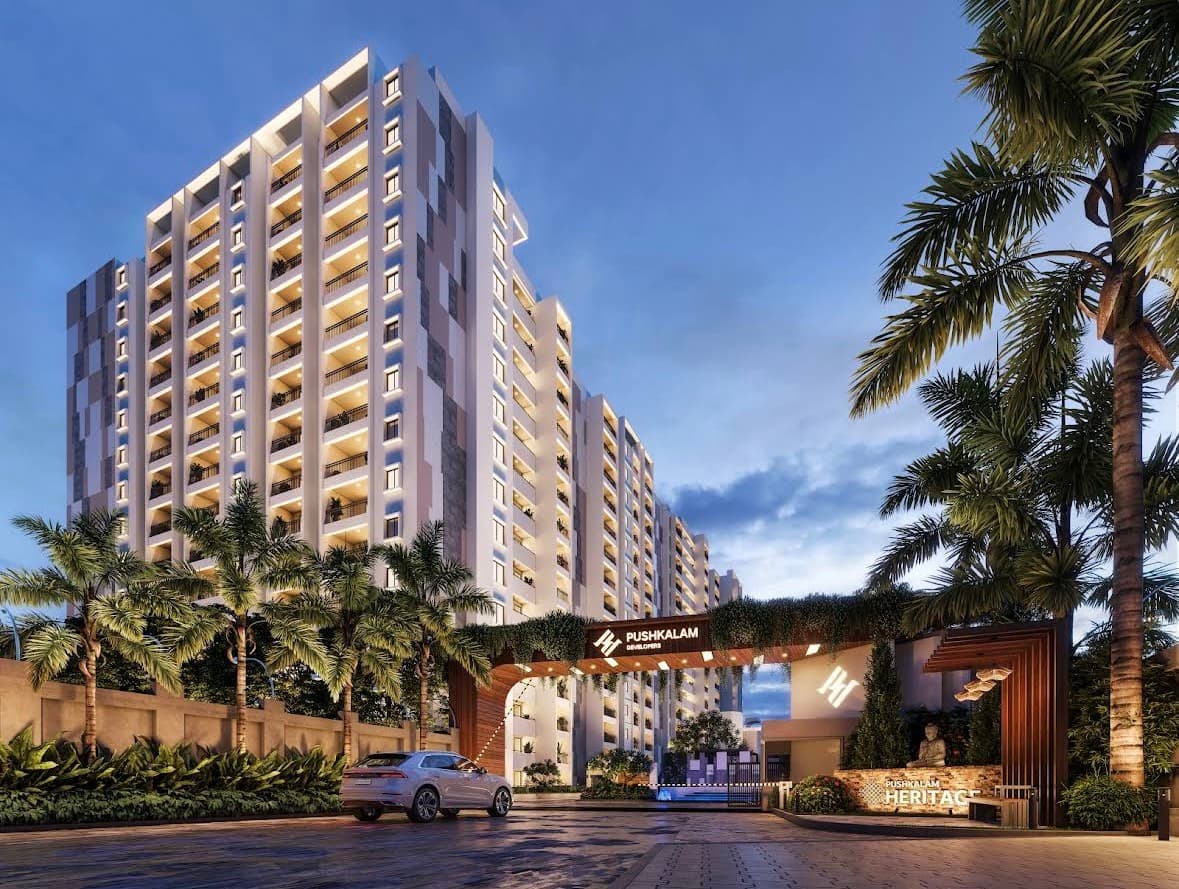
80Anvi Score
Pushkalam Heritage
Budigere Cross, Bangalore
₹1.30 Cr
Onwards
2BHK, 3BHK1310 sqft
EMI questions, answered
Common questions about home loan EMI calculations and repayment planning.
What is EMI and how is it calculated?
EMI (Equated Monthly Instalment) is the fixed amount you pay every month to repay your home loan. It is calculated using the formula: EMI = P × r × (1+r)^n ÷ ((1+r)^n − 1), where P is the principal loan amount, r is the monthly interest rate, and n is the total number of months.
What happens to my EMI if interest rates change?
For floating rate home loans, when the RBI changes the repo rate, your lender typically adjusts either the EMI amount or the loan tenure. Most lenders extend or shorten the tenure while keeping the EMI constant. You can use this calculator to compare your EMI at different interest rates.
Should I choose a shorter or longer loan tenure?
A shorter tenure means higher EMIs but significantly lower total interest paid. A longer tenure lowers your monthly outgo but you pay much more in interest over time. A common approach is to take a longer tenure for flexibility but make periodic prepayments to reduce the outstanding principal faster.
Does making a prepayment reduce my EMI or tenure?
Most lenders let you choose, and the choice matters. Keeping the same EMI shortens the loan and saves the most interest; lowering the EMI eases your monthly cash flow but saves less. On a ₹50 lakh, 20-year loan at 7.5%, prepaying ₹10 lakh after year 5 and keeping the EMI at ₹40,280 ends the loan 5 years 2 months early and saves about ₹15.18 L in interest. Keeping the end date instead drops the EMI to about ₹31,010 and saves about ₹6.69 L. If you do not need the cash flow, shortening the loan is almost always the better use of the money.
Why is so much of my early EMI interest?
Interest is charged on what you still owe, and at the start you owe the whole loan. Your EMI is fixed, so it pays that interest first and only the remainder repays the loan. On a 20-year loan, only about a quarter of the first year's payments reduce what you owe. As the balance falls, interest takes a smaller share each year. This is also why prepaying in the first few years saves far more than prepaying near the end.
Can I claim tax benefit on home loan EMI?
Under the old tax regime, yes. Section 24(b) lets you deduct the interest component of your EMI up to ₹2 lakh a year on a self-occupied home, and Section 80C covers the principal repayment within its overall ₹1.5 lakh limit. The new regime, now the default for salaried taxpayers, allows neither for a self-occupied home; only interest on a let-out property can still be set against its rental income. Compare both regimes before assuming the saving.
What is the ideal EMI-to-income ratio for a home loan?
Banks typically approve home loans where the total EMI across all loans does not exceed 40–50% of your net monthly income. For financial comfort, personal finance advisors recommend keeping your home loan EMI below 30–35% of your take-home pay, leaving room for other expenses and savings.
Keep planning
Pre-EMI Calculator
Buying under construction? See what you pay before possession.
Home Loan OD Calculator
How parking surplus cash in an overdraft account cuts this interest.
Stamp Duty Calculator
State-wise stamp duty and registration charges on your purchase.
Hidden Costs Calculator
GST, khata, deposits and the charges nobody quotes upfront.
Rent vs Buy Calculator
Whether buying beats renting over your actual holding period.
AI Investment Score
Score the project you are buying into before you commit.