Financial Tools · Rental
Rental Yield Calculator.
Gross yield, net yield after costs, and whether the rent actually justifies the price you are being asked to pay.
The rental property
What it earns
Your net rental yield
2.46%
After empty months and costs you keep about ₹1.23 L a year (₹10,250 a month) on a ₹50 L price. Before those, the gross yield is 3.36%.
Gross yield
3.36%
Kept a year
₹1.23 L
Rent repays the price in
30 yrs
Healthy for Bengaluru (3.4% gross)
In the upper half of what Bengaluru flats typically earn. Indian city flats typically earn about 2–4% gross, and Bengaluru is usually in the upper half.
What your money earns here, and elsewhere
Rent is only part of what a property earns. The rest is price growth, which is a guess, so it is shown separately.
- Rent, after costs2.5%
- Rent plus 6% a year price growth8.5%
- Bank deposit6.5%
- Home loan interest (what borrowing costs)7.5%
Rent after costs Price growth (your assumption) Reference rate
Rent alone earns less than a bank deposit
₹50 L in a 6.5% deposit would pay ₹3.25 L a year. This flat pays ₹1.23 L after costs. To match the deposit on rent alone it would need to let for about ₹32,364 a month (it is ₹14,000). Most city flats do not, which is why people buy them for growth as well as rent.
With 6% growth the total is about 8.5% a year
That is 2.5% of rent plus 6.0% of price growth, against 6.5% from a deposit. Growth is not guaranteed: at 3% a year the total would be 5.5%, and at 9% it would be 11.5%.
Each extra empty month costs ₹14K
That is 0.28 points of yield. A tenant who stays for years is worth more than a slightly higher rent.
How rental yield works
- 1
Gross yield is rent against price
A year of rent divided by what the property costs. ₹14,000 a month on a ₹50 lakh flat is ₹1.68 lakh a year, which is 3.36%.
- 2
Net yield is what you keep
Take off the months with no tenant and the costs you pay: property tax, repairs, finding tenants. Brochures quote gross; your bank account sees net.
- 3
Then compare it
A yield means little alone. Set it against a bank deposit, against what a loan on the property costs, and against how much the price may grow.
Free advisory
A 2.46% net yield. We can tell you if that holds.
A yield is only as good as the rent behind it. We track what Bengaluru localities actually let for, year on year, and score every project on the fundamentals that decide whether today’s rent survives the next tenant — free to buyers.
Brokerage
ZERO
RERA
VERIFIED
Projects analysed
BENGALURU-WIDE
Built to be let out
Browse all listingsBengaluru homes with rental demand behind them.
A yield is only as good as the tenant who pays it. These are RERA-verified Bengaluru projects, each scored on location, builder track record and rental fundamentals.
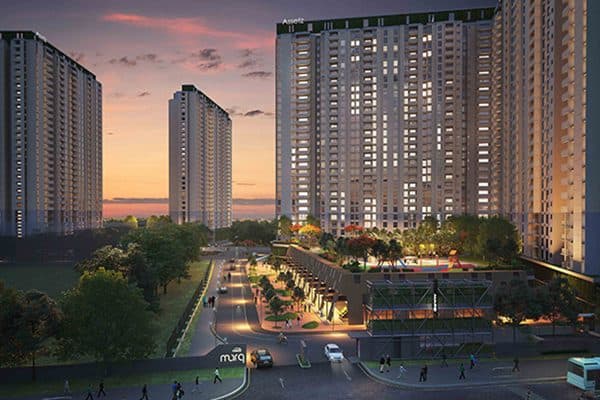
ready to_move
90Anvi Score
Assetz Marq - Resale
Whitefield, Bangalore
₹2.50 Cr
Onwards
3BHK, 4BHK, 2BHK1 sqft
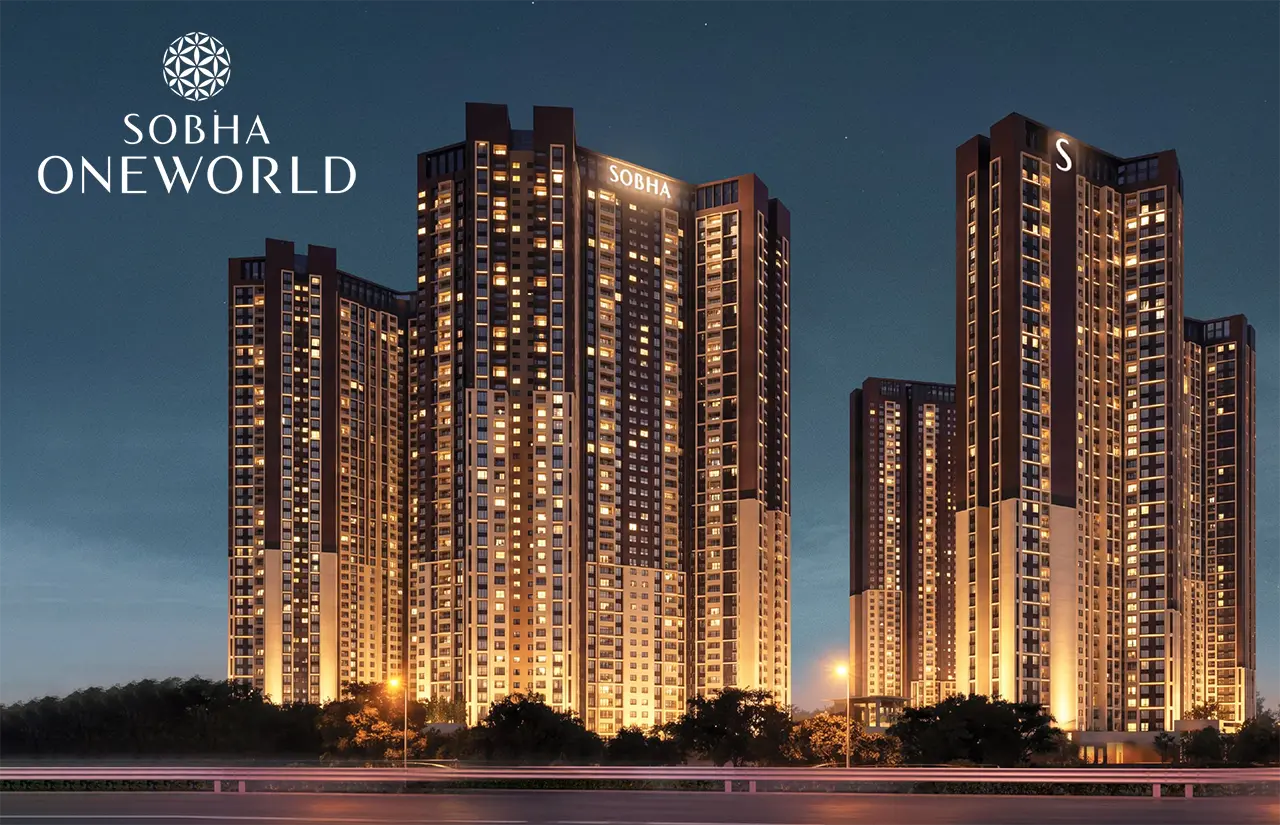
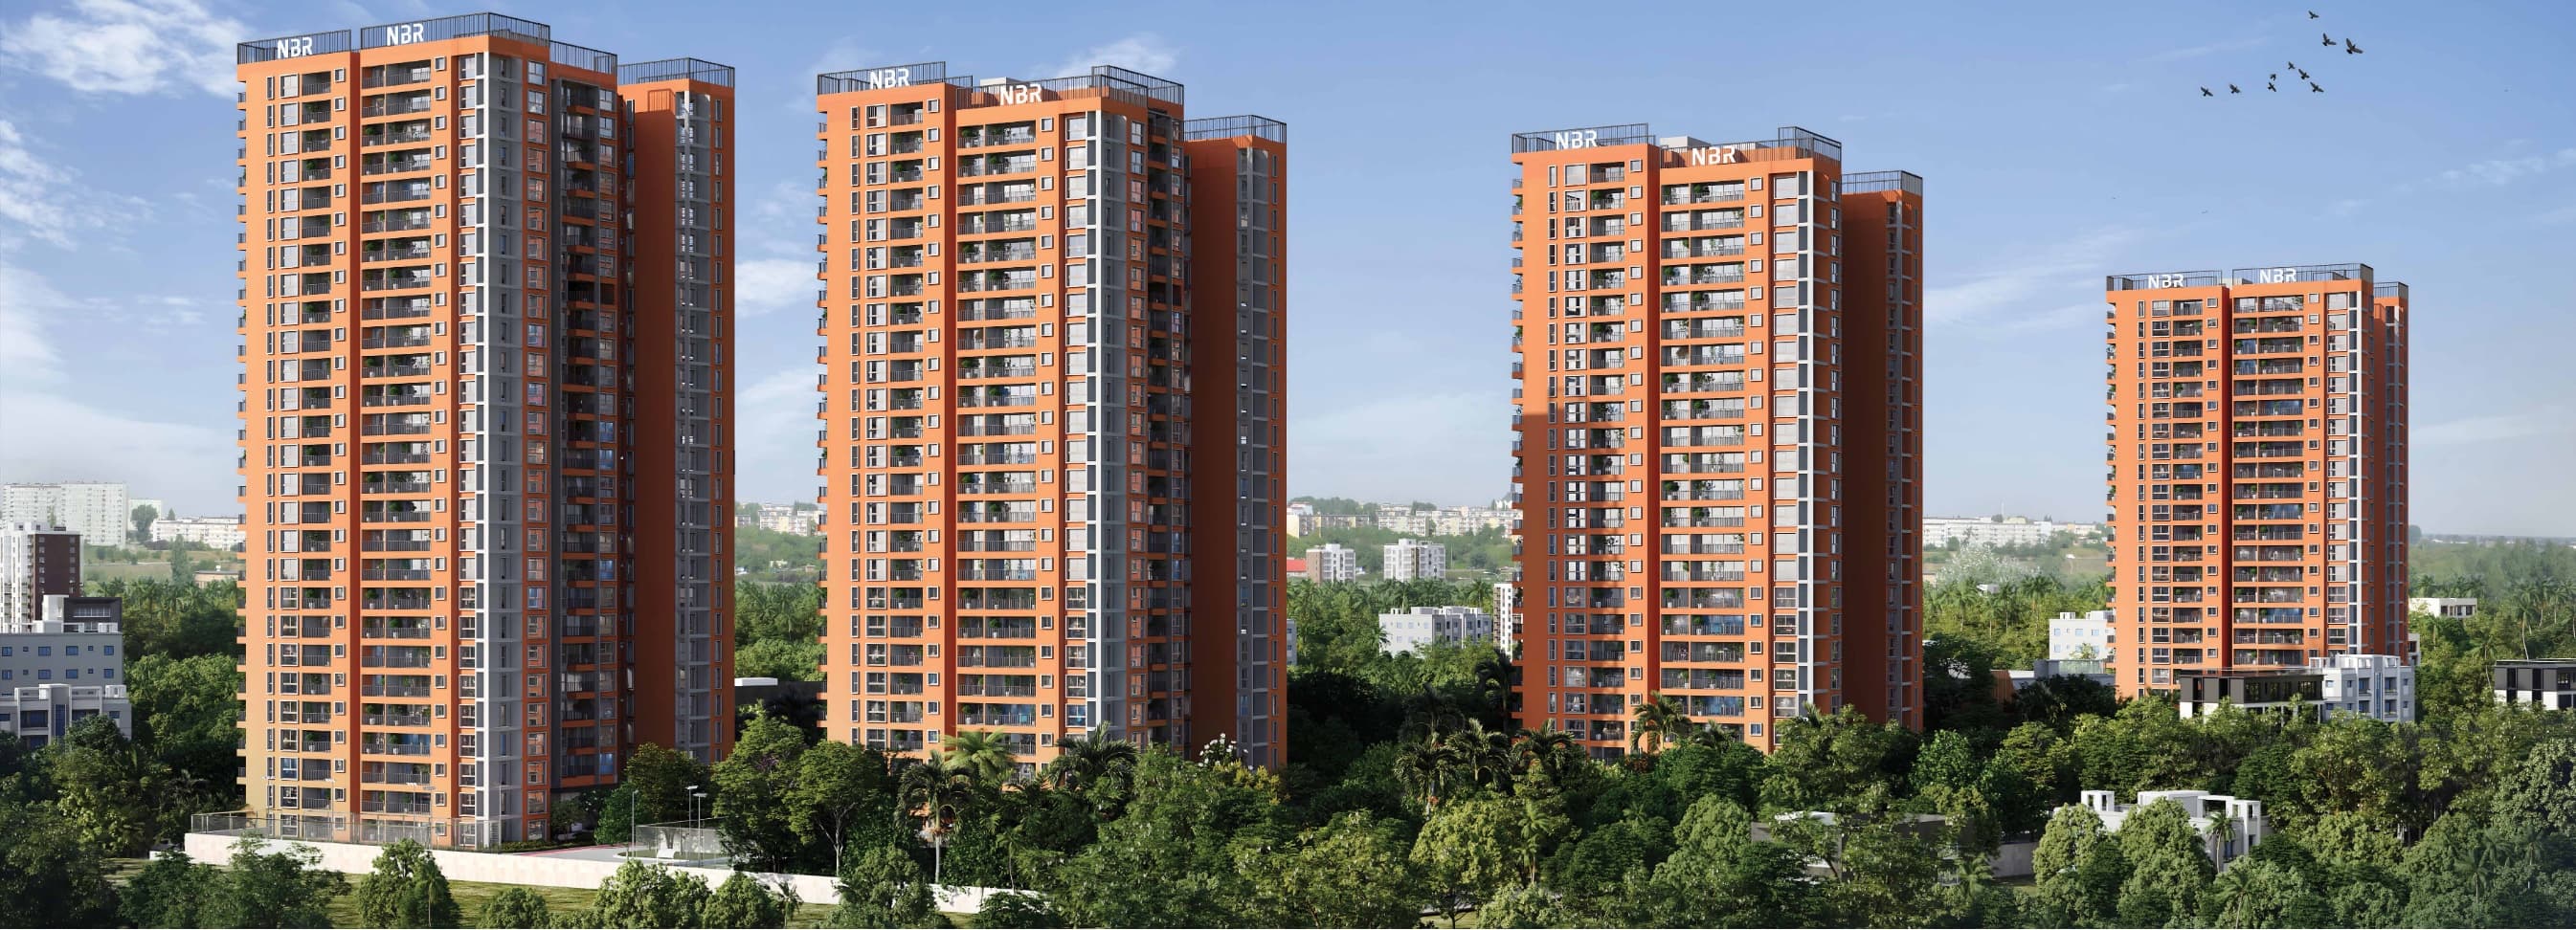
under construction
85Anvi Score
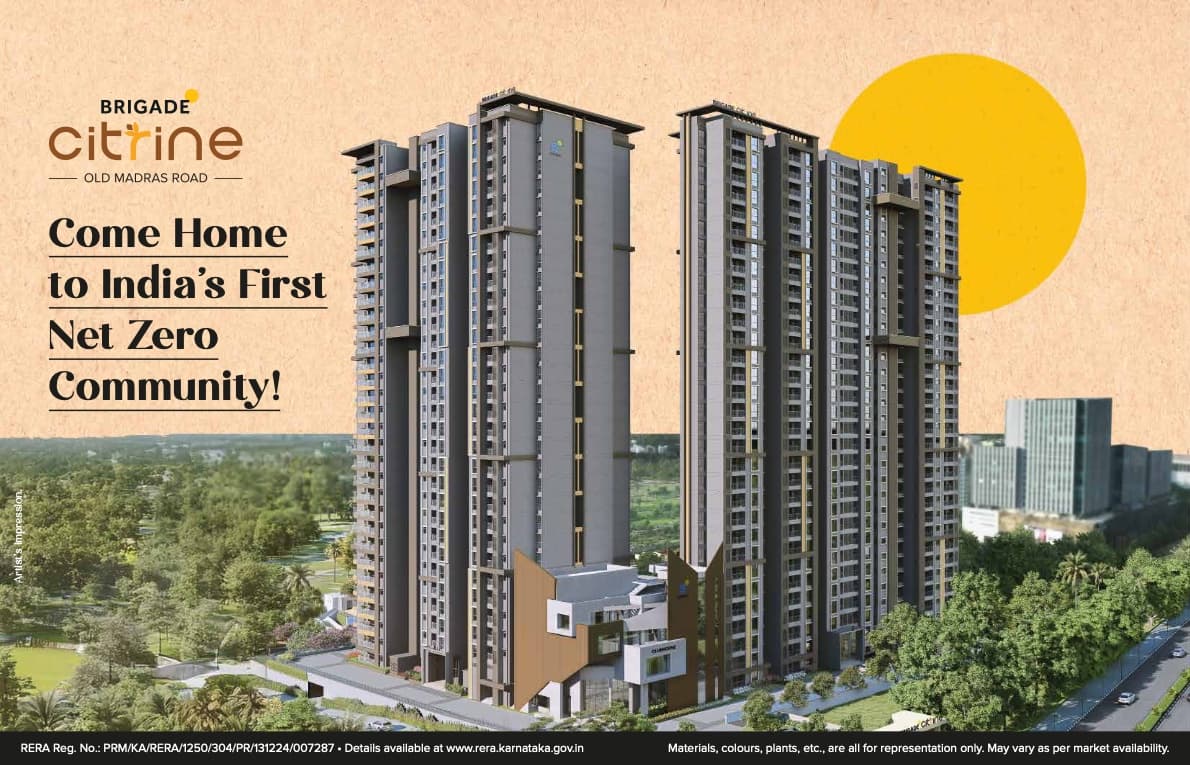
Brigade Citrine
Budigere Cross, Bangalore
₹2.07 Cr
Onwards
3BHK, 4BHK1738 sqft
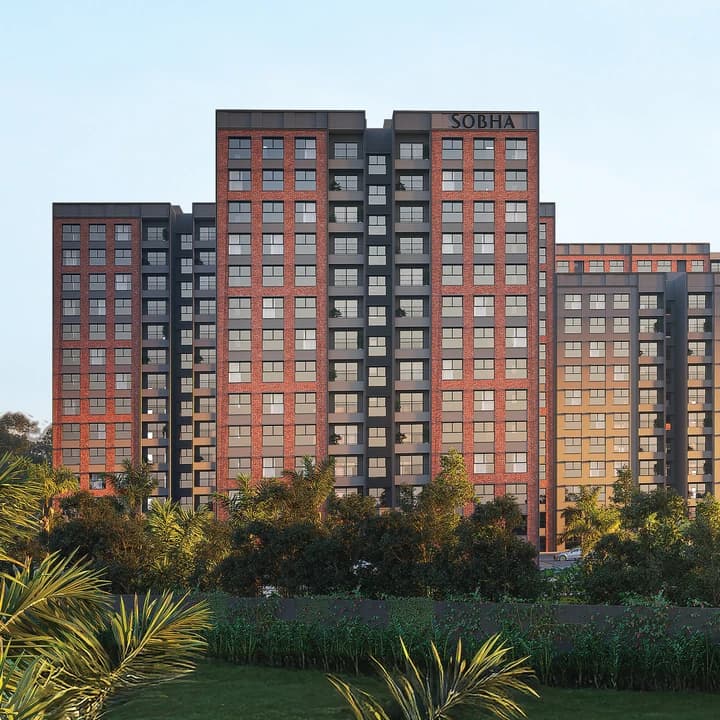
under construction
80Anvi Score
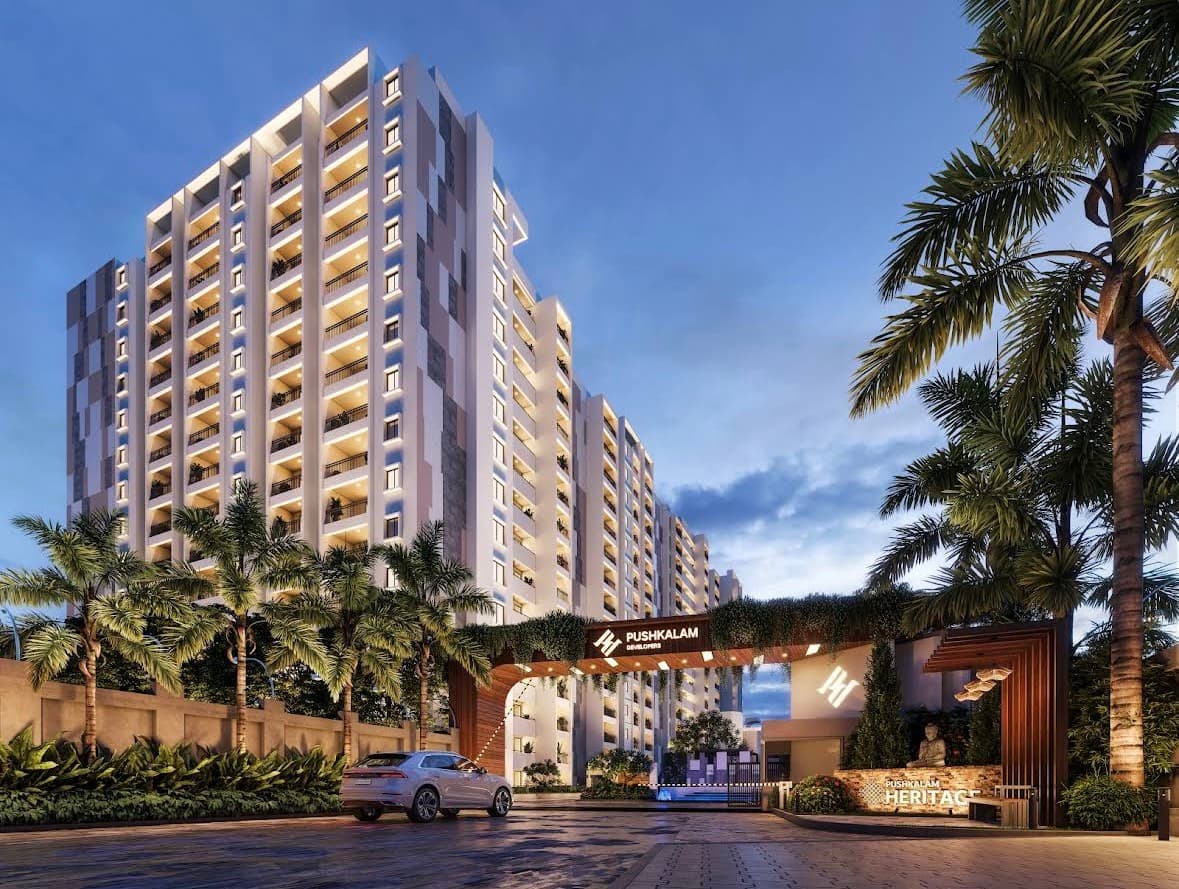
Pushkalam Heritage
Budigere Cross, Bangalore
₹1.30 Cr
Onwards
2BHK, 3BHK1310 sqft
Rental yield questions, answered
Common questions about rental yield and how to evaluate a buy-to-let investment.
What is rental yield and how is it calculated?
Rental yield is the annual rental income expressed as a percentage of the property's purchase price. Gross yield = (Annual Rent ÷ Property Value) × 100. Net yield subtracts ongoing costs like maintenance, property tax, and vacancy periods from the annual rent before dividing.
What is the difference between gross and net rental yield?
Gross yield uses total rental income before expenses. Net yield deducts annual costs — maintenance, property management, insurance, property tax, and periods when the property is vacant. Net yield gives a more realistic picture of actual returns.
What is considered a good rental yield in Bangalore?
Indian city flats typically earn about 2–4% gross, and Bengaluru usually sits in the upper half of that range because of steady demand from tech employers. Well-located flats near large office corridors tend to be at the higher end. A gross yield above roughly 4.5% is high enough that you should confirm the rent with a signed lease or nearby listings before relying on it. After empty months and the costs an owner pays, net yield is commonly 2.5–3.5%. A yield is only half of a property's return, so it is not a verdict on its own.
Does rental yield vary by property type?
Yes. Smaller units (1 BHK, 2 BHK) tend to deliver higher rental yields relative to their purchase price compared to larger luxury units or villas. Commercial properties and co-living spaces often command higher yields but come with different risk profiles.
Should I look at rental yield or capital appreciation?
Ideally both. High-yield properties in peripheral areas may offer lower capital appreciation, while premium central locations offer lower yields but stronger long-term appreciation. The right balance depends on whether you need regular income now or are building long-term wealth.
Why does my flat earn less than a bank deposit?
Because most city flats are bought for price growth as well as rent. A ₹50 L flat letting for ₹14,000 a month keeps about ₹1.23 L a year after one empty month and the owner's costs, a net yield of 2.5%. The same ₹50 L in a 6.5% deposit would pay ₹3.25 L. The gap is meant to be closed by the price rising, which is a hope, not a certainty. The calculator shows the rent, the deposit and your assumed growth side by side.
Will the rent cover my home loan EMI?
Usually not in full. With a 70% loan on that ₹50 L flat at 7.5% over 20 years, the EMI is about ₹28,196 a month, while the rent leaves about ₹10,250 after costs. That covers 36% of the EMI, so you would top up about ₹17,946 a month. The flat would have to let for about ₹33,577 to pay its own EMI. Switch the calculator to "With a home loan" to try your own numbers.
Keep planning
Bangalore Rent Tracker
Check your assumed rent against what the locality really gets.
Resale Value Calculator
Project what your property could be worth when you exit.
Home Loan EMI Calculator
Monthly instalment, total interest and the full repayment schedule.
Hidden Costs Calculator
GST, khata, deposits and the charges nobody quotes upfront.
Rent vs Buy Calculator
Whether buying beats renting over your actual holding period.
AI Investment Score
Score the project you are buying into before you commit.